Chapter 2 - The Ledger of Omissions
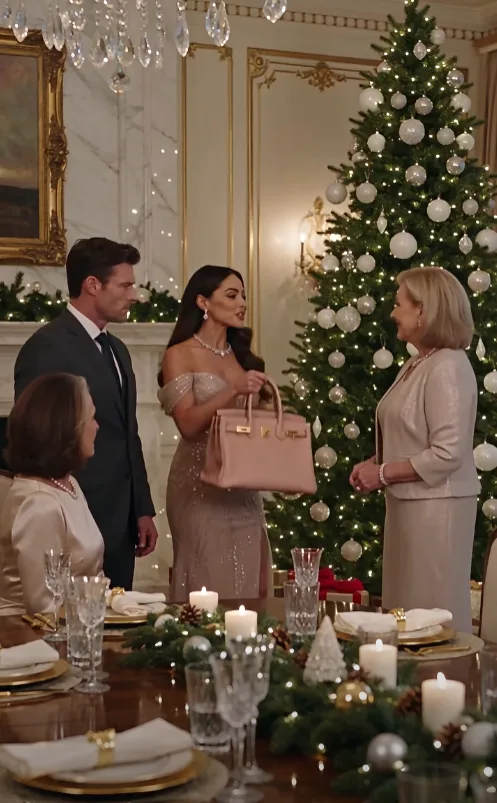
The morning sun cast pale, long shadows across my kitchen floor. I woke up naturally at six o'clock, just as I had for decades. There was no coffee brewing for an ungrateful daughter-in-law, no anxious fluttering in my chest wondering if the roast beef was tender enough or if the table settings looked modern enough for Brooke’s critical eye.
I made a single cup of black coffee in my favorite chipped ceramic mug—the one Matthew had painted for me in second grade, which Brooke had banished to the back of the pantry during her last "kitchen reorganization" under the guise of decluttering. I sat at my small wooden table and looked out the window at the snow-dusted pine trees in the backyard.
My phone, resting beside the mug, remained ominously quiet for the first hour. Then, at 7:30 AM, it lit up.
It wasn't Matthew. It was my bank’s mobile notification app flashing on the screen.
“Alert: Zelle transfer of $5,000.00 from account ending in 4892 processed on 05/14.”
No, that was old. But looking below it, my account balance stared back at me with stark reality. The $5,000 Matthew had borrowed last spring—supposedly to tide him over through a temporary cash-flow crunch at his consulting firm—was supposed to be a bridge loan. A bridge loan that had now stretched across seven months without a single mention of repayment, while Brooke shopped for multi-thousand-dollar luxury leather goods to gift her own mother.
I picked up the phone and opened my digital banking portal. I scrolled back through the transaction history, tracing the lines of my generosity like an archaeologist excavating the ruins of my own foolishness.
Last July: $1,200 for their "spontaneous" weekend getaway to Napa Valley, because Matthew claimed Brooke was stressed and needed a break. Last September: $850 for property tax assistance on their oversized suburban home—a home they insisted on buying to keep up appearances with Brooke’s affluent circle of friends, despite Matthew privately confessing to me over the phone that their mortgage payments were suffocating them.
Every single time they fell short, they came to me. And every single time, I reached into the savings account Daniel and I had built through thirty-two years of careful budgeting, overtime shifts at the post office, and quiet sacrifices. I had believed that protecting my son meant shielding him from the consequences of his own financial mismanagement. I thought I was being a good mother.
Now, looking at the numbers, I saw the ugly truth: I wasn't protecting him. I was subsidizing their lifestyle while they treated me like an embarrassing, out-of-touch fixture they kept around for holiday cooking and emergency loans.
At 8:15 AM, the phone finally rang. Caller ID: Matthew.
I let it ring through. The cheerful default marimba tone played out its full cycle until it hit voicemail. I watched the screen go dark.
Thirty seconds later, it lit up again. Another call from Matthew. I let it go to voicemail again.
Then came a text message:“Mom, pick up. What is going on? Why didn’t you sleep at the house? Brooke is crying because she says you left in a huff over nothing, and now you’re ignoring our calls. This is ridiculous. Call me right now.”
I stared at the words on the screen, feeling a cold detachment wash over me. Brooke is crying. Of course she was. Not because she had humiliated an old woman on Christmas night, but because her audience had walked off the stage, disrupting the carefully curated narrative where she was the generous, gracious hostess and I was the obedient, silent background prop.
I set the phone face down on the table, finished my coffee, and walked over to my desk in the corner of the living room. I opened the top drawer, pulled out a yellow legal pad and a black ink pen, and began to write.
It wasn't an angry letter. It was an inventory.
Item one: The $5,000 personal loan disbursed on May 14th, supported by the bank transfer confirmation number and Matthew’s text message reading: “Don’t worry, Mom, I’ll have this back to you by the end of summer when the Q3 bonuses clear.” Item two: The $1,200 Napa Valley travel expense. Item three: The $850 property tax check written directly to the county collector on their behalf.
Total sum: $7,050.
I wrote down the exact dates, the check numbers, and the digital receipt references. When I finished, I underlined the total twice. Then, I drafted a formal, polite, and completely emotionless demand letter. No tears. No pleading for my son’s love. Just a clear business transaction between a creditor and a debtor.
May you like
As I sealed the papers inside a standard manila envelope, a knock sounded at my front door. It wasn't a tentative, polite knock. It was Matthew’s heavy, impatient rap—the exact same rhythm he used when he was a teenager demanding to be let inside after staying out past curfew.
I didn't rush. I walked slowly across the hardwood floor, untied my apron, tossed it onto the kitchen counter, and reached for the doorknob.