Chapter 4 - The Foreclosure Notice
The notification didn't come by email or phone call. It arrived on Tuesday morning at 8:15 AM in the form of a certified priority envelope delivered directly to my office by a courier in a brown uniform.
I was sitting at my desk on the twentieth floor of the downtown office tower, staring at a quarterly revenue projection spreadsheet that made about as much sense as ancient hieroglyphics, when my executive assistant, Brenda, tapped lightly on my glass door and slid the heavy manila envelope across the polished walnut surface.
"Certified mail, Margaret," Brenda said, her eyes lingering for a second on the return address in the corner. "Looks like it's from a law firm down in Provo. You want me to toss it in the shredder or log it?"
"Leave it, Brenda. Thanks," I said.
She nodded and slipped back out, closing the glass door with a soft click.
I picked up a stainless-steel letter opener, slit the top edge of the envelope, and slid out a formal, legal document printed on thick, cream-colored bond paper bearing the letterhead of Sterling, Vance & Cross Attorneys at Law.
My eyes scanned the dense legal jargon, skipping past the case numbers and property descriptions until they hit the bold header: NOTICE OF PENDING DEFAULT AND INTENT TO ACCELERATE FORECLOSURE.
According to the legal filing, the residential property located at 4412 Oakridge Lane—my childhood home—was currently carrying a delinquent balance of $14,250 in missed secondary mortgage payments, plus penalties, accumulative interest, and unpaid county property taxes dating back to the previous fiscal year. Unless the full arrears balance was satisfied within fourteen business days, the lending institution, Alpine Mutual Bank, would initiate trustee sale proceedings, putting the home up for public auction by mid-January.
I dropped the paper onto the desk as if it were coated in hot grease.
My phone buzzed immediately. It wasn't Mom this time. It was a local Salt Lake area code I didn't recognize. I let it ring out to voicemail. Five seconds later, my email client pinged with an urgent message flagged with a red exclamation point.
Subject: PLEASE READ — EMERGENCY REGARDING OAKRIDGE PROPERTY
It was from Dana.
Margaret, please stop ignoring our calls. Mom hasn't slept in three days. She’s been crying on the kitchen floor since Sunday night. Dad’s blood pressure hit 180 over 110 yesterday, and the doctor said if he has another stroke, it’s on your hands. The lawyers are saying Alpine Mutual is moving fast because of some technical default clause triggered by the missed auto-draft. You caused this! You’re the one who pulled the plug! All you have to do is call your bank, reverse the cancellation, and wire the back-pay. It’s chump change to you! Why are you trying to make our family homeless over a stupid grudge about Thanksgiving?
I stared at the screen, a cold, bitter smile touching the corners of my mouth.
A stupid grudge.
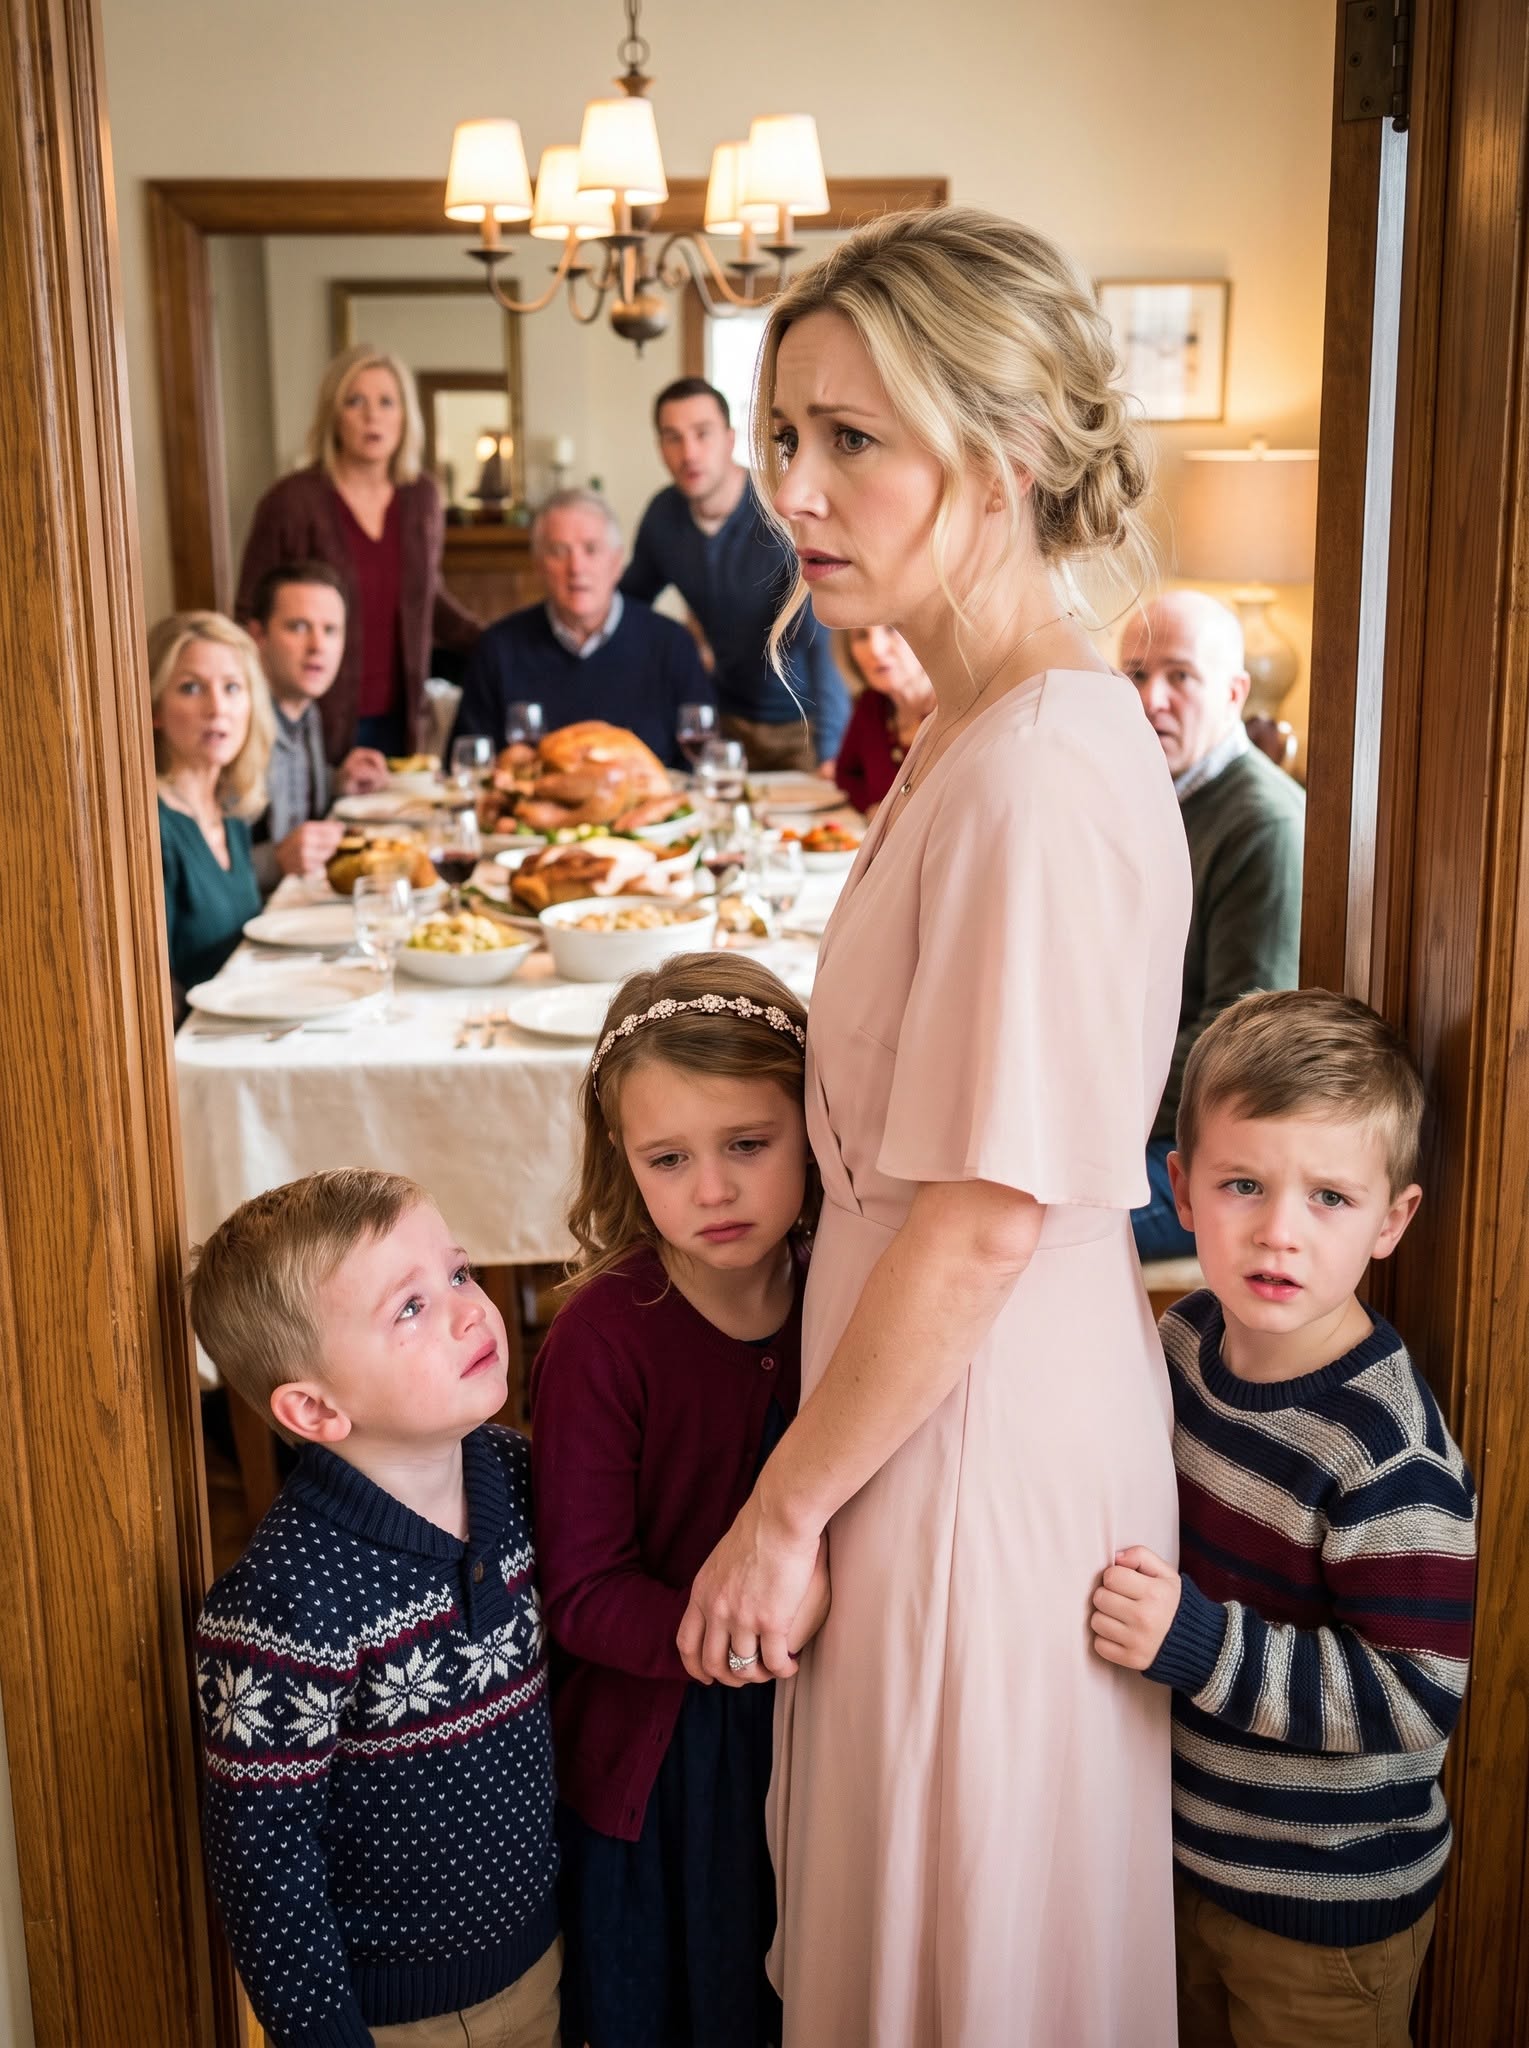
To them, locking three children out in a freezing snowstorm while they feasted on a stolen Thanksgiving turkey was just a minor administrative friction. To them, my four years of financial sacrifice weren't an act of love or filial duty; they were an entitlement—a birthright they were owed simply because I had managed to build a successful career while Dana had married a man whose business model consisted of taking out high-interest loans against other people's real estate.
My phone rang again. This time it was Dad.
I picked up the receiver, pressed speakerphone, and let it sit there while I went back to reviewing my spreadsheet.
"Margaret?" Dad’s voice came through the speaker, raspy, weak, and dripping with the practiced, manipulative guilt of a man who hadn't worked a forty-hour week since the Reagan administration. "Honey... are you there? Your mother is beside herself. I can't bear to see her like this. We're old people, Margaret. We raised you. We put food on your table. And now... because of some misunderstanding over dinner... you're going to let the bank take the roof over our heads?"
I stopped typing. The cursor blinked rhythmically on the screen.
"Dad," I said, my voice eerily quiet. "Let's talk about the house."
There was a brief pause on the other end, the sound of static and heavy breathing. "What... what about the house?"
"Let's talk about how the house was paid off in nineteen-ninety-eight," I said, my tone as steady as a glacier. "Let's talk about how in two-thousand-fourteen, you took out a two-hundred-thousand-dollar equity loan to bail out Mark’s car dealership. Let's talk about how every single cent I sent you for four years—fifty-two thousand dollars of my personal money—wasn't going toward your heart medication or your groceries, but was servicing a debt created by your son-in-law’s corporate incompetence."
Silence. Absolute, suffocating silence on the line.
"How... how do you know about that?" Dad stammered, the theatrical frailty instantly dropping from his voice, replaced by the panicked, cornered tone of a child caught stealing from the cookie jar.
"I know because I read the legal notice that just arrived at my office twenty minutes ago," I said. "And here is my final answer, Dad. I am not wiring a single red cent. I am not calling Alpine Mutual Bank. And if you and Mom want to save your house, I suggest you call Mark and tell him to sell his country club membership, sell his wife’s luxury SUV, and start paying off the debt he dragged you into."
"Margaret, you can't be serious!" Dad shouted, the old authoritarian bluster roaring back to life. "We are your family! Blood is thicker than water! You have a moral obligation—"
May you like
"My moral obligation ended when you locked my nine-year-old son out in the snow so you could eat my turkey with a bunch of strangers," I said.
And I hung up, blocked the number, and went back to work.